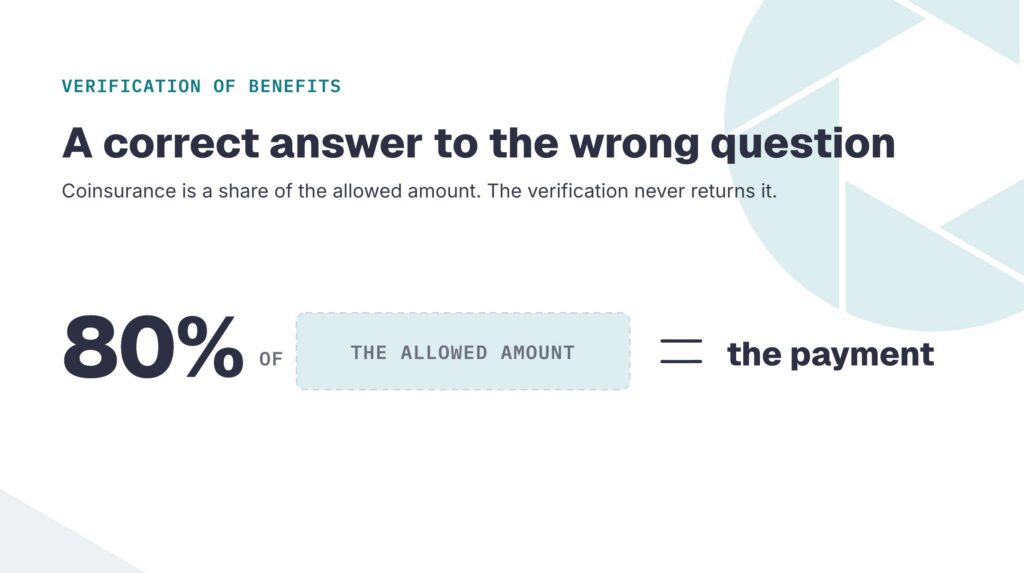
The verification said 80 percent after deductible. The claim paid a fraction of what the admissions team told the family to expect.
Nobody made an error. The verification was correct, the coinsurance really was 80 percent, and the payment was consistent with the plan. The gap sits in a question the verification never answered: 80 percent of what.
That question is the whole difference between confirming coverage and predicting revenue, and it is why PayerLenz real-time eligibility pairs a benchmark with every check rather than treating them as separate lookups.
- A coinsurance percentage applies to the plan’s allowed amount, not to your billed charges.
- Verification returns the percentage. It does not return the number that percentage is applied to.
- “Eligibility verification” and “verification of benefits” are used interchangeably but describe two different operations.
- An accurate verification and an unexpected payment are entirely compatible outcomes.
Two Different Things Wearing One Name
In behavioral health the two terms get swapped freely, which hides a real operational difference. One is an automated transaction. The other is human work.
An automated request and response between your system and the payer, governed by the X12 transaction set standard. It returns coverage status and cost-share structure in seconds. What it can return is bounded by what the standard defines, and provider reimbursement basis is not part of that definition.
In practice, a worked verification. Often a phone call to the payer, producing a completed worksheet that captures detail the electronic response either omitted or returned ambiguously. It is slower and more expensive per case, and it is the only route for the questions a transaction cannot carry.
Both answer whether coverage exists. Neither answers what the payer will pay, because that figure is not a benefit attribute at all. It is a pricing decision the plan makes when the claim arrives.
What an Electronic Check Actually Returns
It is worth being precise about this, because the electronic response is more useful than skeptics allow and less complete than optimists assume.
- Coverage status, in seconds rather than on hold
- Deductible and out-of-pocket detail, in-network and out-of-network
- Behavioral health cost-share specifically, not just the medical benefit
- Authorization indicators, so you know when a gap is coming
- Carve-out indicators, which tell you the claim is going somewhere else
- The allowed amount your coinsurance percentage will apply to
- The reimbursement method the plan uses to price out-of-network care
- Any figure you could put in front of a family as an expected rate
- Confirmation that authorization was actually obtained
The carve-out indicator deserves attention because it changes where the claim goes. When a check detects a behavioral health carve-out, the useful next step is rerunning the check against the carve-out administrator rather than proceeding on a response from a plan that will not adjudicate the claim.
Eighty Percent of What
This is the mechanic behind almost every surprised phone call after an EOB arrives.
Coinsurance is expressed as a percentage of the allowed amount. The allowed amount is what the plan decides the service is worth, set by whichever pricing method applies to that plan, and it is frequently well below what was billed.
That term has a settled definition. The federal glossary definition of allowed amount describes it as the maximum a plan will pay for a covered service, with any balance above it not counting toward the patient’s deductible or out-of-pocket maximum.
So 80 percent after deductible is 80 percent of a number the verification never disclosed. If the allowed amount lands low, an accurate 80 percent produces a payment that looks nothing like 80 percent of the bill.
This is the specific reason a verification can be entirely correct while the payment feels wrong. The percentage was right. The base it applied to was never in the answer, and quoting a family a figure derived from billed charges builds an expectation the claim cannot meet.
Where the Missing Number Comes From
The allowed amount is not knowable in advance with certainty, but it is far from unknowable. Claims that have already adjudicated under the same plan characteristics describe the range it tends to fall in.
That is what a benchmark is. A distribution across matched adjudicated claims for a given payer group, state, level of care, and reimbursement method, read with the claim count behind it.
Putting that range beside the eligibility response gives admissions both halves of the answer in one place, which is what the reimbursement benchmarks search returns. Coverage from the payer, and expected reimbursement from claims history.
When a Live Call Is Still Worth It
Electronic checks handle most cases well. A worked verification earns its cost in a narrower set, and knowing which is which protects the time of an admissions team on the phone.
Order a live VOB worked by our team when the electronic response comes back thin or contradictory, when a carve-out is indicated and the administrator is unclear, when the plan is a complex out-of-network design, and when the admission is high enough in value that being wrong is expensive.
Below that threshold the call usually does not pay for itself. Treating every case as a phone case is how verification teams end up as a bottleneck on admissions.
Keep the Record, Because Memory Will Not Hold
Verification results are evidence, and they stop being evidence the moment nobody can produce them. A payment dispute six weeks after admission turns on what the payer actually said on the day.
Electronic eligibility results are retained for 30 days and then permanently deleted, which is a deliberate handling choice rather than a limitation. Anything worth keeping past that window has to be exported at the time.
The practical habit is to export the result for any admission above whatever dollar threshold your team sets, and to attach it to the case rather than leaving it in a system that is designed to forget.
What to Do With a Payment That Disagrees
Start by separating the two possible failures. Either the verification was wrong, which is rare, or the allowed amount was lower than anyone assumed, which is common.
Compare the payment against claims that share the plan’s characteristics rather than against the billed amount. A payment inside the expected range for its own cohort is working as designed, however unwelcome it feels.
A payment well below the 25th percentile for that cohort is a different matter, and that is the one worth raising with the payer.
Does a VOB Tell You What the Payer Will Pay?
No. A verification confirms that coverage is active and describes the cost-share structure. It does not return the allowed amount, which is the figure that determines payment, and it does not return the pricing method the plan uses.
What Is the Difference Between Eligibility Verification and a VOB?
Eligibility verification is an automated transaction returning coverage and cost-share in seconds. A verification of benefits, as the term is normally used in behavioral health, is human work, usually a call, producing a fuller worksheet. They answer overlapping but different questions.
Why Did We Get Paid Less Than the Verification Indicated?
Most often because coinsurance applies to the allowed amount rather than to billed charges. An accurate 80 percent of a low allowed amount produces a payment far below 80 percent of the bill.
Can Anything Tell You the Allowed Amount in Advance?
Not with certainty. Adjudicated claims for the same payer group, state, level of care, and reimbursement method describe the range it tends to occupy, which is a range rather than a promise.
Start free with 15 historical searches at signup. No credit card required.
Get 15 Free Searches